What is the difference between C Corp, S Corp, and LLC?
Compare C Corp, S Corp, and LLC differences in taxation, ownership, and management. Review their advantages, drawbacks, and formation requirements.
Compare C Corp, S Corp, and LLC differences in taxation, ownership, and management. Review their advantages, drawbacks, and formation requirements.

By Brad Nakase, Attorney
Email | Call (800) 484-4610
Have a quick question? We answered nearly 2000 FAQs.
Depending on a number of factors, including the scale of the company, its potential for expansion, the way it is run, how the proprietors want the taxation to be, & many more, business owners may set up their organizations in a variety of ways. You may seek advice on which business structure works the best for you. Anyone beginning a business ought to consult with a trained tax expert. A tax attorney or an accountant might be helpful. However, it is helpful to know a few of the elements that usually affect such decisions.
Numerous business owners are curious about the many kinds of business ownership and the way to choose the best one for their company. The most frequent queries potential business owners ask about the various arrangements to set up a company in the US are listed below. In this article, our California business startup attorney discusses factors to take into account when contemplating whether form a business as a C corp, S corp, or LLC.
There are five different ways that new businesses can be established: partnerships, LLCs (limited liability companies), sole proprietorships, S corporations, or C corporations.
S corps (S corporations) and C corps (C corporations) are among the popular business configuration kinds. Each structure has pros and cons, and while S and C corps get taxed differently, there are some parallels between them.
C corps as well as S corps:
Although both S and C corporations have advantages and disadvantages, which one most effectively meets your needs depends on your company’s objectives and characteristics.
An LLC, C Corp, or S Corp is not intrinsically “better”; rather, they merely specify how a business is taxed & the regulations it must follow to be in compliance with the IRS. The type, size, and objectives of the firm in consideration all play a major role in how one might incorporate.
Although it’s not always true, S corps are often smaller enterprises or single proprietorships, and C corps are typically larger businesses. When it pertains to choosing the best tax classification for expanding mid- and small-sized businesses, including limited liability companies (which we will talk about later), there is, in fact, a lot of gray area.
In general, a C corporation, designated as such because it is included in the IRS code’s subchapter “C,” is a separate legal organization that is held by its stockholders and has limitless development potential. Since a C corporation is a legal entity that permits unlimited expansion through stock offerings (making them attractive to investors) & is perfect for big, retail-based firms, the majority of large corporations and public enterprises are established as C corporations.
The fact that C corporations are liable to double taxes is another characteristic that sets them apart. This implies that all dividends or earnings that the business distributes to its stockholders are subject to an additional taxation as individual income after the corporation is first charged at the corporate tax (federal) rate of twenty-one percent. Avoiding double taxation is actually among the strongest arguments for filing as an S corporation (more about that later).
Forming a C corporation has numerous advantages, the majority of which are related to tax advantages & development methods. However, the complexity of a C corporation typically necessitates consultation with legal and tax experts to assist with federal and state filing obligations, in addition to papers like the Incorporation Certificate & bylaws, making the process of incorporating one costly. The bill is also increased by labor and management expenses, and the complexity and cost of a business increase with its size.
Positively, a C Corporation can:
The following are some drawbacks of creating a C corporation:
However, establishing a C corporation can be the greatest option for business owners who see a firm with room to develop and plenty of investment options.
Establishing a C corporation requires a dedication to the business’s objectives and success, in addition to some challenging and time-consuming work.
The following actions must be taken by a company owner to create a C corporation:
Step 1: Give the company a unique name. It has to be unique and one that nobody else is utilizing.
Step 2: Select corporate officers. They are the governing board and a CEO.
Step 3: Submit the organization’s incorporation documents to the state secretary. It is filed with the state in which it is incorporated.
Step 4: Create the bylaws of the company.
Step 5: Give stockholders stock certificates.
Step 6: Obtain the necessary business permits.
Step 7: To obtain an EIN, send IRS Application SS-4.
A lot of consideration and action are needed for these processes. For these and numerous other reasons, creating a C corporation is a challenging process that usually entails speaking with an accountant and investing in software to guarantee precise tax filings once the business is operational. Instead, the simpler choice of forming an S Corp might be preferred by many business owners.
A corporate structure that chooses to flow/pass through taxed earnings, deductions, losses, & credits to the shareholders is known as an S Corp (Subchapter S, IRS). They are favored mainly because S corporations are appealing to sole proprietors and small firms, offer alluring tax benefits, and shield personal property from liabilities.
Because S corporations are regarded as “pass-through companies,” their taxable income is not subject to federal taxation. Instead, since S corporations are not subject to federal taxes, they “flow through” straight to the individual tax returns of the company’s owners and stockholders, preventing double taxation. Instead, S Corp proprietors are liable for federal individual income tax on revenues or profits ranging from 10 to 39.6%, in addition to a maximum of 13.3% local and state income taxes.
S corporation owners can save a lot of money on taxes by reporting business profits, losses, credits, & deductions on their individual tax returns. In fact, S Corporation shareholders may deduct as much as 20 percent of QBI under the Tax Cuts & Jobs Act, thereby lowering a person’s tax bill by between 20 and 25 percent. The S corporation structure not only saves taxes but also shields the owners’ private assets from lawsuits and debt collections aimed at the S corporation.
Operating an S corporation has a number of benefits and also some drawbacks.
The following are some benefits of establishing an S corporation:
An S corporation has the following drawbacks:
You should compare LLC vs. S Corp in California to understand your options. Although an S corporation’s restrictions may deter prospective investors and make it challenging to obtain money, they might also draw in investors who seek closer ties to the company.
However, not every kind of firm can decide to become an S corporation. For example, financial organizations, insurance businesses, and multinational companies are not allowed to be S corporations. Additionally, compared to other corporate forms like a limited liability company or LLP, S corporations are subject to higher compliance obligations. Additionally, if S corporation owners fail to maintain thorough records or fail to provide their workers a wage that the Internal Revenue Service considers “fair,” they may face legal repercussions.
Although it is simpler to form an S corporation than a C corporation, there are still a number of stages that are similar.
The following are the fundamental steps in forming an S corporation:
Step 1: Select a company name and confirm that the name is not being used by any other companies.
Step 2: Submit the corporation’s address, name, objective, main operations, and owner’s name together with the papers of incorporation to the state.
Step 3: Choose the chairman, vice chairman, secretary, & treasurer of the governing board.
Step 4: Create governance bylaws that specify the shareholders’ rights and obligations. (An attorney’s assistance is recommended for this phase because there are regulatory ramifications.)
Step 5: You ought to obtain an EIN to submit federal taxes, employ workers, & file for permits and licenses.
Step 6: Submit Form 2553 to select the official S corporation status. It must be signed by each shareholder.
Step 7: Pay local and state filing costs and acquire the necessary local and state business licenses.
The actual job of developing the company and fulfilling annual and quarterly reporting requirements starts as soon as the S corporation is established. It is also necessary to have regular board & shareholder meetings, record minutes, take note of decisions, and maintain accurate and current corporate records. Even when they constitute the only worker and board member of the S corporation, sole proprietors are nevertheless subject to these regulations.
S or C corps can seem excessively complicated in terms of corporate structures, particularly to sole proprietors or owners of small businesses. If your company is tiny, you might want to continue operating as the sole proprietor, making every business decision and keeping all profits. However, if you work as an independent contractor or freelancer, failing to set up a corporate structure could jeopardize your private assets in the event that, for example, a client opts to file a lawsuit against you.
An LLC, which has become the most popular structure of organization for small firms, is an alternative if you want to safeguard your private assets but do not wish to create an S or C corp. The choice between an LLC vs. S Corp in California can affect how your business is taxed.
An LLC is a type of corporate structure that shields the personal assets of the company’s owner from the liabilities or obligations of the company. LLCs can be as small as sole proprietorships or as large as companies with several hundred workers. For instance, a lot of legal firms are limited liability companies, and independent freelancers or contractors may choose to create a limited liability company to protect their personal belongings from debt collection or lawsuits aimed at the company. You ought to learn the key differences between LLC vs. S Corp in California before starting your business.
There are additional reasons to form an LLC besides safeguarding a company owner’s private wealth, chief among them being that they are simpler to set up.
Establishing an LLC has the following benefits:
Although LLCs don’t need to maintain thorough records, it’s still crucial to maintain correct books & accounts. You must compare LLC vs. S Corp in California in detail to understand your options.
The following are the drawbacks of creating an LLC:
You should first educate yourself on the LLC regulations in your state because LLCs are governed at the state level. Nonetheless, the majority of governments follow these fundamental procedures:
Step 1: Select a company name that incorporates the “LLC” acronym.
Step 2: Submit an application for an EIN or IRS Tax Identification.
Step 3: To find out how to file organization documents and obtain any licenses or permissions your state may need, go to the government’s official website.
Step 4: Draft the operating agreement. It is to guarantee the LLC’s legal protection and to make the organization’s structure and regulations clear.
Step 5: You must learn about the LLC tax reporting requirements in your state. Certain states impose additional unique taxes on certain types of businesses, such as hotels or tobacco and cannabis companies.
Step 6: Submit the state filing costs in step six.
Step 7: Choose whether the LLC is going to operate as a single proprietorship, C corporation, or S corporation.
Regardless of the choice you select, it is difficult to run a small enterprise, so ensure that you possess the necessary legal tools on hand to establish and administer an LLC. Additionally, you are subject to greater self-employment taxation as a limited liability company owner. It is something that many business owners attempt to avoid. Luckily, the S corporation structure offers strategies to reduce the financial burden of taxes on self-employment.
LLC owners may lower their personal taxes on self-employment by maintaining the LLC model while switching to a C or S corporation tax classification. The 15.3% self-employment tax includes 2.9 percent for Medicare & Social Security’s 12.4 percent. The limited liability company owner’s individual tax rate varies from 10 to 37% based on their tax bracket. It is added to all of it.
Consider a scenario where an LLC operator has ten thousand dollars in company expenses & $125k in gross income. It sounds excellent that the LLC operator makes $115k in profits. Nevertheless, the LLC operator now has to cover the $115k in individual income tax & 15.3 percent self-employment tax, minus any deductions.
Because of a substantial income tax (corporate) rate of 21 percent, most owners of a limited liability company will not want to operate as a C corporation. However, they may opt to file as an S corporation to benefit from lower personal tax rates. Due to new developments in tax laws, a limited liability company owner filing as an S Corp might be allowed to benefit from the QBI deduction. It enables filers to subtract up to 20 percent of company earnings from their tax bill. However, this does imply that a limited liability company owner must comply with certain IRS rules pertaining to S corporation status.
All business executives should ask themselves the same questions to decide which structure of ownership is best for their company. This is regardless of the type of organization. Selecting the company structure shouldn’t be done carelessly. You ought to consider carefully what kind of enterprise you want to launch and run. Weigh your options & select the option that best suits your company’s objectives.
A tax expert or attorney can help simplify the filing procedure and guarantee that all of the requirements are completed, regardless of the business form being considered. The next step is for company owners to implement their plan.
Have a quick question? We answered nearly 2000 FAQs.
See all blogs: Business | Corporate | Employment
Most recent blogs:
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/10/10-Steps-on-How-to-Start-Up-a-Lifestyle-Brand-Business.jpg
783
1058
claudiap
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
claudiap2026-10-16 04:33:242026-10-16 04:33:26How to Start a Lifestyle Brand Business in 10 Steps
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/10/How-to-Add-a-Partner-to-an-Existing-Business.jpg
786
1056
claudiap
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
claudiap2026-10-16 03:44:352026-10-16 03:44:36How to Add a Partner to an LLC
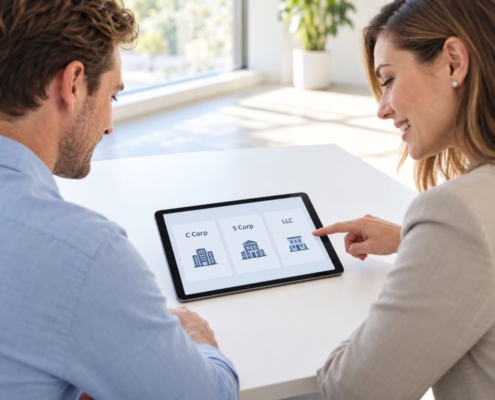 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/10/What-is-the-difference-between-C-Corp-and-S-Corp-and-LLC.jpg
796
1057
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-10-16 03:39:142026-10-16 03:39:15What is the difference between C Corp, S Corp, and LLC?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/10/What-Is-a-Lease.jpg
777
1054
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-10-16 03:33:552026-10-16 03:33:56What Is a Lease? Definition, Types, and Key Requirements
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/09/What-is-an-equity-partner-at-a-law-firm.jpg
786
1057
claudiap
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
claudiap2026-09-16 03:06:032026-09-16 03:06:05What is an Equity Partner at a Law Firm and How Much Does an Equity Partner Make?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/09/What-Is-Equitable-Estoppel-in-California.jpg
792
1071
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-09-16 02:27:132026-09-16 02:27:15What Is Equitable Estoppel in California?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/09/Form-941-New.jpg
742
573
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-09-16 02:23:242026-09-16 02:24:05What Is Form 941? Filing Requirements, Deadlines, and Instructions
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/09/What-Is-an-Annual-Report-for-an-LLC.jpg
792
1054
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-09-16 02:15:342026-09-16 02:15:35What Is an Annual Report for an LLC?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/09/What-Is-a-Competitor-Company-Business-Definition-and-Examples.jpg
801
1062
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-09-16 02:11:592026-09-16 02:12:01What Is a Competitor Company? Business Definition and Examples
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/Best-Free-Payroll-Software-for-Small-Businesses-and-Startups-in-2026.jpg
791
1199
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-08-31 11:38:042026-08-31 11:38:27Best Free Payroll Software for Small Businesses and Startups in 2026
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/How-To-Start-A-Restaurant.jpg
792
1163
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-08-31 11:07:032026-08-31 11:10:16How to Open a Restaurant in 2026
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/Average-Small-Business-Revenue.jpg
786
1194
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-08-31 09:57:062026-08-31 09:57:07Average Small Business Revenue and Owner Income
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/How-to-Start-a-Digital-Marketing-Agency.jpg
779
1062
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-08-13 03:21:522026-08-13 03:21:53How to Start a Digital Marketing Agency in 2026
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/How-To-Setup-A-Virtual-Business-Address-For-LLC.jpg
786
1418
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-08-13 02:28:242026-08-13 02:28:25How To Set Up A Virtual Business Address For LLC
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/What-is-a-Promissory-Note.jpg
778
1055
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-08-13 02:23:222026-08-13 02:23:23What Is a Promissory Note? How It Works for a Personal Loan
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/How-To-Find-My-EIN-Number.jpg
797
1050
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-07-31 13:22:542026-07-31 13:22:55How To Find Your Business EIN Number
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/Business-Acumen-Definition-Importance-and-Ways-to-Develop-It.jpg
798
1052
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-07-31 13:17:192026-07-31 13:17:20Business Acumen: Definition, Importance, and Ways to Develop It
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/How-to-Open-a-Bar-Starting-a-Bar-Business.jpg
795
1056
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-31 12:58:572026-07-31 12:58:59How to Open a Bar: Starting a Bar Business
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/What-Do-Corporate-Lawyers-Do.jpg
792
1059
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-07-31 12:48:362026-07-31 12:48:37What Do Corporate Lawyers Do?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/What-is-a-Mechanics-Lien-Key-Facts-and-Legal-Implications.jpg
790
1184
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-11 06:22:032026-07-11 06:22:04What is a Mechanic’s Lien? Key Facts and Legal Implications
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/When-are-S-Corp-Shareholders-Entitled-to-Shareholder-Distributions.jpg
788
1049
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-07-11 06:11:382026-07-11 06:11:39When are S-Corp Shareholders Entitled to Shareholder Distributions?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/How-to-Start-a-Taxi-Business-in-2026.jpg
780
1391
claudiap
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
claudiap2026-07-09 08:34:102026-07-09 08:34:18How to Start a Taxi Business in 2026
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/What-is-a-Business-Partnership-Meaning-and-Types.jpg
779
1412
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-07-09 08:17:532026-07-09 08:17:55What is a Business Partnership: Meaning and Types?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/What-Is-Gross-Profit-and-How-Is-It-Calculated-in-Financial-Statements.jpg
787
1189
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-09 08:12:192026-07-09 08:12:20What Is Gross Profit and How Is It Calculated in Financial Statements?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/What-Is-Indemnity-and-How-Does-It-Apply-to-Insurance-Contracts.jpg
800
1055
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-02 08:09:272026-07-02 08:09:29What Is Indemnity and How Does It Apply to Insurance Contracts?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/Best-Self-Employment-Jobs-and-Ideas.jpg
786
1182
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-02 08:00:232026-07-02 08:00:2452 Best Self-Employment Jobs and Business Ideas
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/Steps-on-How-to-Start-a-Small-Restaurant.jpg
786
1417
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-02 07:36:452026-07-02 07:36:468 Steps on How to Start a Small Restaurant
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/How-to-Pay-Yourself-From-An-LLC.jpg
791
1426
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-07-02 06:59:172026-07-02 06:59:18How to Pay Yourself From An LLC?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/Elements-of-Libel-Definitions-Proof-and-Legal-Standards.jpg
783
1055
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-02 06:52:572026-07-02 06:52:58Elements of Libel: Definitions, Proof, and Legal Standards
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/How-to-Pay-Myself-as-a-Sole-Proprietor.jpg
792
1414
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-07-01 12:25:332026-07-01 12:25:34How to Pay Yourself as a Sole Proprietor?
See all blogs: Business | Corporate | Employment