How to Add a Partner to an LLC
How to add a partner to an LLC in California, including member approval and operating agreement updates. Review ownership changes, tax considerations, and documentation.
How to add a partner to an LLC in California, including member approval and operating agreement updates. Review ownership changes, tax considerations, and documentation.

By Douglas Wade, Attorney
Email | Call (800) 484-4610
Have a quick question? We answered nearly 2000 FAQs.
Among the few occasions when an LLC’s documentation is examined while everybody continues to move along is when a new partner comes on board. This article outlines the procedures I follow when preparing updated operating agreements & admission documentation for LLCs in California. You can learn how to add a partner to an LLC with this guide.
Brief response: The admission requirements stipulated in the operating agreement must be followed in order to add an individual to an LLC in California. Every current member must agree if it states nothing. Next, modify the LLC’s membership records, change the existing agreement, register the new member’s investment and percentage, and handle the property tax, tax, & securities ramifications. Documentation with the State is not necessary for a member to be admitted. You may wish to consult with a commercial litigation attorney for concerns on partnership disputes before adding a partner to your company.
Yes, provided that all present members consent or an operating agreement permits it. Following the formation of an LLC, an individual can become a member as specified in an operating agreement, via the merger or other comparable deal, or through the approval of every member.
Since you are “all members” of a one-member LLC, you have decision-making authority. One holdout may prevent entry for an LLC having multiple members without a formal agreement/document. Before you give someone a stake, make sure to review the agreement.
An individual may join without obtaining a movable interest or being required to make a donation. This allows a business to accept an employee-member who has a say but no financial stake, which is rare but occasionally helpful in a household business. You ought to consider how the new member will affect ownership before deciding how to add a partner to an LLC.
The documents are different, and there are 2 ways to get in. The prospective member either purchases all or a portion of a current member’s interest or makes a contribution to the limited liability company in exchange for a new interest.
1. Buy-in (New issuance)
2. Buy-out (Buy from a current member)
There is a trap in a buy. A transferable stake does not grant the transferee the right to vote and take part in governance. If a buyer reimburses a member for some interest but is not admitted, they will only have the right to dividends and no voice.
The LLC is required to maintain an up-to-date list of every member’s & transferee’s address, name, contribution, & loss or profit share in alphabetical sequence. A duplicate of the written operating contract and any modifications is also retained by the LLC. The state does not receive any of these.
Admission of the member does not require any documents. Since the documents of organization do not include members, they don’t require revision. It is the Declaration of Information that is being addressed.
The statement includes the names and addresses of any administrators/managers or, in the absence of a manager, every member of the limited liability company. The LLC might submit an updated statement whenever that information is modified, apart from the agent. A fresh filing is necessary when an agent changes.
The Act does not specify that an applicant must submit within ninety days of registering a member, despite what some websites claim. To ensure that the public register reflects the current owner prior to a financial institution or title business requesting it, continue to file a revised declaration for an LLC managed by members.
It relies on what is stated in the operating agreement, and a vague agreement may lead to an odd outcome. Distributions are determined by the amount of every member’s payments as recorded in the company’s records, unless the agreement specifies otherwise. Unless otherwise specified in the agreement, losses and profits are distributed in the same manner.
Consider Mary, who used $10k to start ABC Bakery LLC 5 years ago. Today, the company is valued at $400k. They agree that Clara will receive 20% of the $100k she brings in. The default approach would award Clara the majority of all distributions if the documents only reflect $10k by Mary & $100k by Clara. Mary’s capital must be recorded at the $400k amount, or the proportions must be stated explicitly in the updated agreement.
Dilution is driven by the same mathematics. After the payment, Clara’s $100k on a $400k business results in a $500k business, and $100k of $500k equals twenty percent. The business would continue to be worth $400k, and Clara’s 20% share would be valued at $80k if Clara had instead given Mary $100k for a portion of her stake.
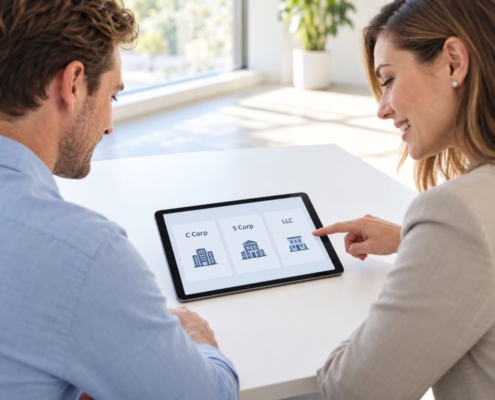
Must Read: What is the difference between C Corp, S Corp, and LLC?
Your CPA ought to examine the transaction before it happens because adding an additional member typically modifies the LLC’s taxation. Unless it chooses otherwise, a 2-member LLC is typically taxed like a partnership, while a one-member LLC is typically exempt from federal income tax. The federal categorization is followed by California.
In general, when someone gives property to the partnership in return for a stake in it, no gain or loss is recorded. Provided the property is covered by that rule. Based on the way the interest is set up, a new participant who receives a percentage rather than cash for future effort might have taxable earnings. Questions to ask your CPA:
If a limited liability company has real estate in California, it can. A shift in possession of the real estate the limited liability company owns occurs when an individual or organization acquires a majority stake interest in the LLC via a transfer or purchase of interests. Once initial co-owners transferred collectively over fifty percent ownership stake in the entity that obtained the asset in an exempted transfer, a different rule reevaluates the property.
A modification in ownership declaration must be submitted to the Equalization Board by the acquiring party within ninety days after the shift in control. It is generally safe to add a twenty percent participant to a standard LLC that possesses a building. A count is required when admitting multiple people at once or adding a person who subsequently purchases more. You must learn how to add a partner to an LLC & keep your business compliant.
Most probably yes if the newly appointed member isn’t going to be in charge. According to securities law, a stake in a limited liability company is considered a “security,” with the exception of membership interests in which the claimant can demonstrate that every member is actively involved in management. Voting rights and information rights by themselves do not prove that, according to the same provision.
In California, except when the purchase is exempt or qualified, it is illegal to sell or offer securities in an issuance transaction. Minor private sales are exempt, although there are restrictions. Consult a lawyer before accepting a check from a family member or friend who will be considered an inactive investor.
Not because they joined. An LLC’s liabilities are the LLC’s obligations and do not become an individual’s debts just because someone serves as a member. In the absence of an individual assurance or the type of violation that allows a court to pierce the veil, the newly appointed member’s money in a business is at risk, but their personal possessions are typically not. Before making an investment, an incoming member ought to still want to view the business’s loan records, leases, & any claims. Also, business owners ought to fully understand how to add a partner to an LLC.
The members of an LLC own personal property. Thus, the operating contract and California state laws specify the procedures that must be followed in order to remove a member. A withdrawal notification, a vote by majority, or a process outlined in the documents of incorporation may be utilized to expel an individual from the LLC. It might be necessary to reimburse the individual in consideration for his portion of the membership interests. You might have to go to court when a member refuses to accept a purchase offer or depart the LLC.
When one member departs, their interests must be addressed; how this is determined by your agreement. Any well-written operating agreement defines whether the limited liability company or the members who remain buy out the retiring member’s interest, the way the interest in question is valued, and the manner in which payment is made (frequently in conjunction with the buy-sell clause).
Without those conditions, you find yourself dealing with California’s defaults and possible disputes about the value of the interest plus the rights of the outgoing member. A member’s departure is made orderly rather than controversial by planning this ahead of time, either as a component of the operating contract or a supplementary buy-sell arrangement.
Prior to deeming the admission final, make sure you have:
Keeping accurate internal oversight is the major goal of properly accepting a new member. You may maintain LLC compliance & establish a transparent ownership track by submitting your contractual paperwork first. This is followed by any required state filings.
1. Is it possible to add someone to an LLC with just one member?
Yes. The LLC enters a partnership for income tax (federal) reasons. The exception is when it chooses corporation status. You modify the existing agreement, verify your state’s reporting requirements, and manage the tax transition.
2. Does the LLC’s taxation alter when a member is added?
Yes. An LLC with just one member is ignored. It submits Form 1065. It is automatically categorized as a partnership when the LLC is multi-member.
3. You added a new member: Is a fresh EIN required?
Not when the limited liability company already has an EIN of its own. It stays with the LLC. In the event that the LLC uses the proprietor’s number, it needs to obtain an EIN.
4. What tax ramifications result from a new member joining an LLC?
It is contingent upon how the individual joins. If a new member purchases a portion of your investment, you might have to pay taxes on the profit. Generally speaking, a new individual’s contribution to the limited liability company for a fresh interest is not taxed. In both situations, the LLC begins submitting partnership returns.
5. How can I include investors in my LLC?
You need to modify the existing agreement. You should specify the investor’s percentages, rights, and profit sharing, & manage the partnership’s tax returns in the exact same manner as a new member. For taxation reasons, investors constitute members.
6. Can a new member be added by majority members without everyone’s approval?
Only if permitted by an operating agreement. In the absence of a condition like this, all members must agree to admittance following formation. A setting in an agreement that should be changed is that.
7. Does the company’s EIN change when a member is added?
Not for an LLC with several members & that has already filed as a type of partnership. Have a CPA verify the EIN concern before acceptance. The IRS guidelines do not specifically cover a one-member LLC.
Have a quick question? We answered nearly 2000 FAQs.
See all blogs: Business | Corporate | Employment
Most recent blogs:
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/10/10-Steps-on-How-to-Start-Up-a-Lifestyle-Brand-Business.jpg
783
1058
claudiap
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
claudiap2026-10-16 04:33:242026-10-16 04:33:26How to Start a Lifestyle Brand Business in 10 Steps
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/10/How-to-Add-a-Partner-to-an-Existing-Business.jpg
786
1056
claudiap
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
claudiap2026-10-16 03:44:352026-10-16 03:44:36How to Add a Partner to an LLC
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/10/What-is-the-difference-between-C-Corp-and-S-Corp-and-LLC.jpg
796
1057
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-10-16 03:39:142026-10-16 03:39:15What is the difference between C Corp, S Corp, and LLC?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/10/What-Is-a-Lease.jpg
777
1054
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-10-16 03:33:552026-10-16 03:33:56What Is a Lease? Definition, Types, and Key Requirements
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/09/What-is-an-equity-partner-at-a-law-firm.jpg
786
1057
claudiap
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
claudiap2026-09-16 03:06:032026-09-16 03:06:05What is an Equity Partner at a Law Firm and How Much Does an Equity Partner Make?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/09/What-Is-Equitable-Estoppel-in-California.jpg
792
1071
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-09-16 02:27:132026-09-16 02:27:15What Is Equitable Estoppel in California?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/09/Form-941-New.jpg
742
573
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-09-16 02:23:242026-09-16 02:24:05What Is Form 941? Filing Requirements, Deadlines, and Instructions
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/09/What-Is-an-Annual-Report-for-an-LLC.jpg
792
1054
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-09-16 02:15:342026-09-16 02:15:35What Is an Annual Report for an LLC?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/09/What-Is-a-Competitor-Company-Business-Definition-and-Examples.jpg
801
1062
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-09-16 02:11:592026-09-16 02:12:01What Is a Competitor Company? Business Definition and Examples
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/Best-Free-Payroll-Software-for-Small-Businesses-and-Startups-in-2026.jpg
791
1199
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-08-31 11:38:042026-08-31 11:38:27Best Free Payroll Software for Small Businesses and Startups in 2026
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/How-To-Start-A-Restaurant.jpg
792
1163
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-08-31 11:07:032026-08-31 11:10:16How to Open a Restaurant in 2026
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/Average-Small-Business-Revenue.jpg
786
1194
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-08-31 09:57:062026-08-31 09:57:07Average Small Business Revenue and Owner Income
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/How-to-Start-a-Digital-Marketing-Agency.jpg
779
1062
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-08-13 03:21:522026-08-13 03:21:53How to Start a Digital Marketing Agency in 2026
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/How-To-Setup-A-Virtual-Business-Address-For-LLC.jpg
786
1418
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-08-13 02:28:242026-08-13 02:28:25How To Set Up A Virtual Business Address For LLC
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/08/What-is-a-Promissory-Note.jpg
778
1055
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-08-13 02:23:222026-08-13 02:23:23What Is a Promissory Note? How It Works for a Personal Loan
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/How-To-Find-My-EIN-Number.jpg
797
1050
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-07-31 13:22:542026-07-31 13:22:55How To Find Your Business EIN Number
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/Business-Acumen-Definition-Importance-and-Ways-to-Develop-It.jpg
798
1052
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-07-31 13:17:192026-07-31 13:17:20Business Acumen: Definition, Importance, and Ways to Develop It
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/How-to-Open-a-Bar-Starting-a-Bar-Business.jpg
795
1056
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-31 12:58:572026-07-31 12:58:59How to Open a Bar: Starting a Bar Business
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/What-Do-Corporate-Lawyers-Do.jpg
792
1059
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-07-31 12:48:362026-07-31 12:48:37What Do Corporate Lawyers Do?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/What-is-a-Mechanics-Lien-Key-Facts-and-Legal-Implications.jpg
790
1184
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-11 06:22:032026-07-11 06:22:04What is a Mechanic’s Lien? Key Facts and Legal Implications
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/When-are-S-Corp-Shareholders-Entitled-to-Shareholder-Distributions.jpg
788
1049
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-07-11 06:11:382026-07-11 06:11:39When are S-Corp Shareholders Entitled to Shareholder Distributions?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/How-to-Start-a-Taxi-Business-in-2026.jpg
780
1391
claudiap
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
claudiap2026-07-09 08:34:102026-07-09 08:34:18How to Start a Taxi Business in 2026
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/What-is-a-Business-Partnership-Meaning-and-Types.jpg
779
1412
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-07-09 08:17:532026-07-09 08:17:55What is a Business Partnership: Meaning and Types?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/What-Is-Gross-Profit-and-How-Is-It-Calculated-in-Financial-Statements.jpg
787
1189
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-09 08:12:192026-07-09 08:12:20What Is Gross Profit and How Is It Calculated in Financial Statements?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/What-Is-Indemnity-and-How-Does-It-Apply-to-Insurance-Contracts.jpg
800
1055
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-02 08:09:272026-07-02 08:09:29What Is Indemnity and How Does It Apply to Insurance Contracts?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/Best-Self-Employment-Jobs-and-Ideas.jpg
786
1182
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-02 08:00:232026-07-02 08:00:2452 Best Self-Employment Jobs and Business Ideas
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/Steps-on-How-to-Start-a-Small-Restaurant.jpg
786
1417
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-02 07:36:452026-07-02 07:36:468 Steps on How to Start a Small Restaurant
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/How-to-Pay-Yourself-From-An-LLC.jpg
791
1426
shawna
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
shawna2026-07-02 06:59:172026-07-02 06:59:18How to Pay Yourself From An LLC?
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/Elements-of-Libel-Definitions-Proof-and-Legal-Standards.jpg
783
1055
Amit
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Amit2026-07-02 06:52:572026-07-02 06:52:58Elements of Libel: Definitions, Proof, and Legal Standards
 https://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2026/07/How-to-Pay-Myself-as-a-Sole-Proprietor.jpg
792
1414
Nakase
http://california-business-lawyer-corporate-lawyer.com/wp-content/uploads/2022/05/Nakase-Wade-logo-transparent-200x54px.png
Nakase2026-07-01 12:25:332026-07-01 12:25:34How to Pay Yourself as a Sole Proprietor?
See all blogs: Business | Corporate | Employment